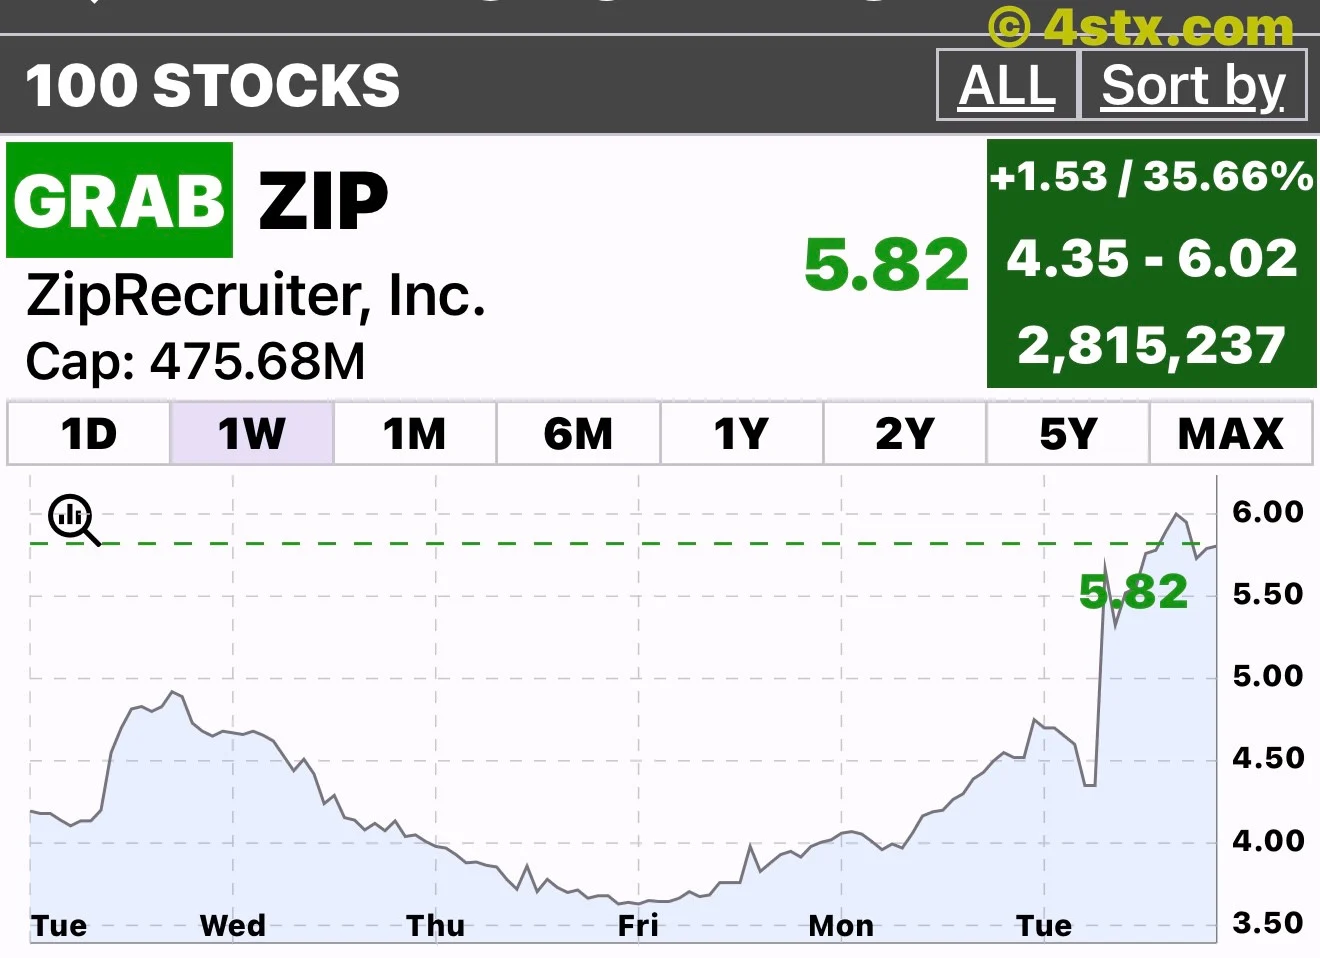
ZipRecruiter’s stock delivered a striking move in the market snapshot reviewed by Stock-App.com: $5.82, up +$1.53, or 35.66%. The image showed volume of 2,815,237 shares and a displayed range of $4.35 to $6.02. Those figures describe the captured screen, not a verified closing price or a live quote; the image does not establish an exact date or timestamp.
The company’s November 9 earnings announcement supplies a concrete business development behind renewed attention to ZIP. The central question is whether an improving recruitment marketplace can sustain its recovery after such a sharp share-price move.
Results give the recovery substance
For the quarter ended September 30, 2026, ZipRecruiter reported $124.4 million in revenue, up 8% year over year, and $20.8 million in adjusted EBITDA. Both exceeded the upper end of management’s guidance. GAAP net income was $5.1 million. ZipRecruiter’s earnings release confirms those results.
An improvement in both sales and earnings makes the report more consequential than a product announcement alone. The business is generating measurable results, giving investors something specific to assess beyond enthusiasm about hiring technology.
Adjusted EBITDA still needs careful handling. It excludes expenses including stock-based compensation and is not interchangeable with net income or available cash. The company’s positive GAAP result therefore deserves attention alongside its larger adjusted figure.
More employers and a growing AI channel
Quarterly paid employers increased 10% from a year earlier to 73,929. Management also said traffic from AI platforms nearly doubled year over year following integrations with ChatGPT and Claude. These figures come from its shareholder letter.
The potential attraction is straightforward: better matches could encourage employers to keep paying for recruitment services. However, rising traffic does not by itself establish how much revenue that channel produces, and management’s engagement claims should remain clearly attributed.
For shareholders, repeat business matters more than a temporary burst of visitors. The useful test is whether improved discovery translates into durable customer relationships and economically attractive hiring outcomes.
The recovery still has weak spots
Revenue per paid employer was $1,683, below $1,717 a year earlier, according to the quarterly filing. The company also had $250.7 million of outstanding debt principal at September 30. Its business remains exposed to labor demand and competition.
That combination leaves meaningful questions. A larger customer base can support expansion, but investors also need to understand customer spending and the cost of winning that business. Lower average revenue is not, by itself, proof that customers are receiving less value.
Similarly, a large daily percentage gain cannot establish what future earnings are worth. The screenshot records price action; it does not demonstrate that the valuation has become attractive.
The next test is delivery
Management expects fourth-quarter revenue of $118 million to $122 million and adjusted EBITDA of $16 million to $20 million. Those are forecasts, not booked results.
The next report will help show whether the momentum persists. Continued customer growth, steadier spending and profits that hold up would strengthen the recovery case. For now, ZIP offers a concrete earnings story with unresolved execution risks. This is market reporting, not a recommendation to buy or sell.