Microvast’s latest report tells a story more serious than a bad quarter. The battery maker is selling less, keeping less profit from each dollar of sales and trying to secure the money needed to keep operating. Those pressures reinforce one another: weaker trading makes a financing solution more important, just as the business has less room for disappointment.
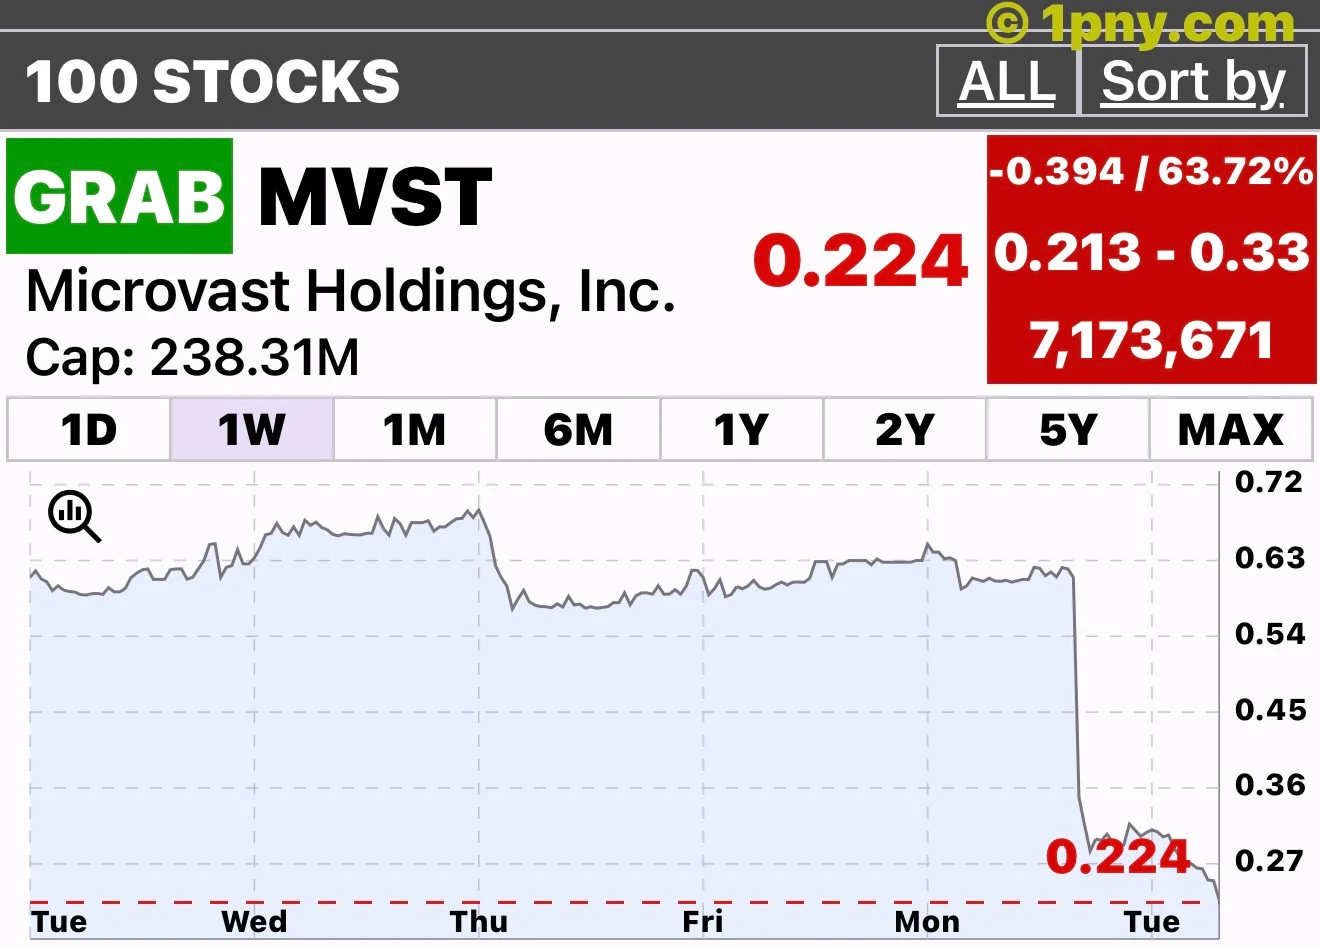
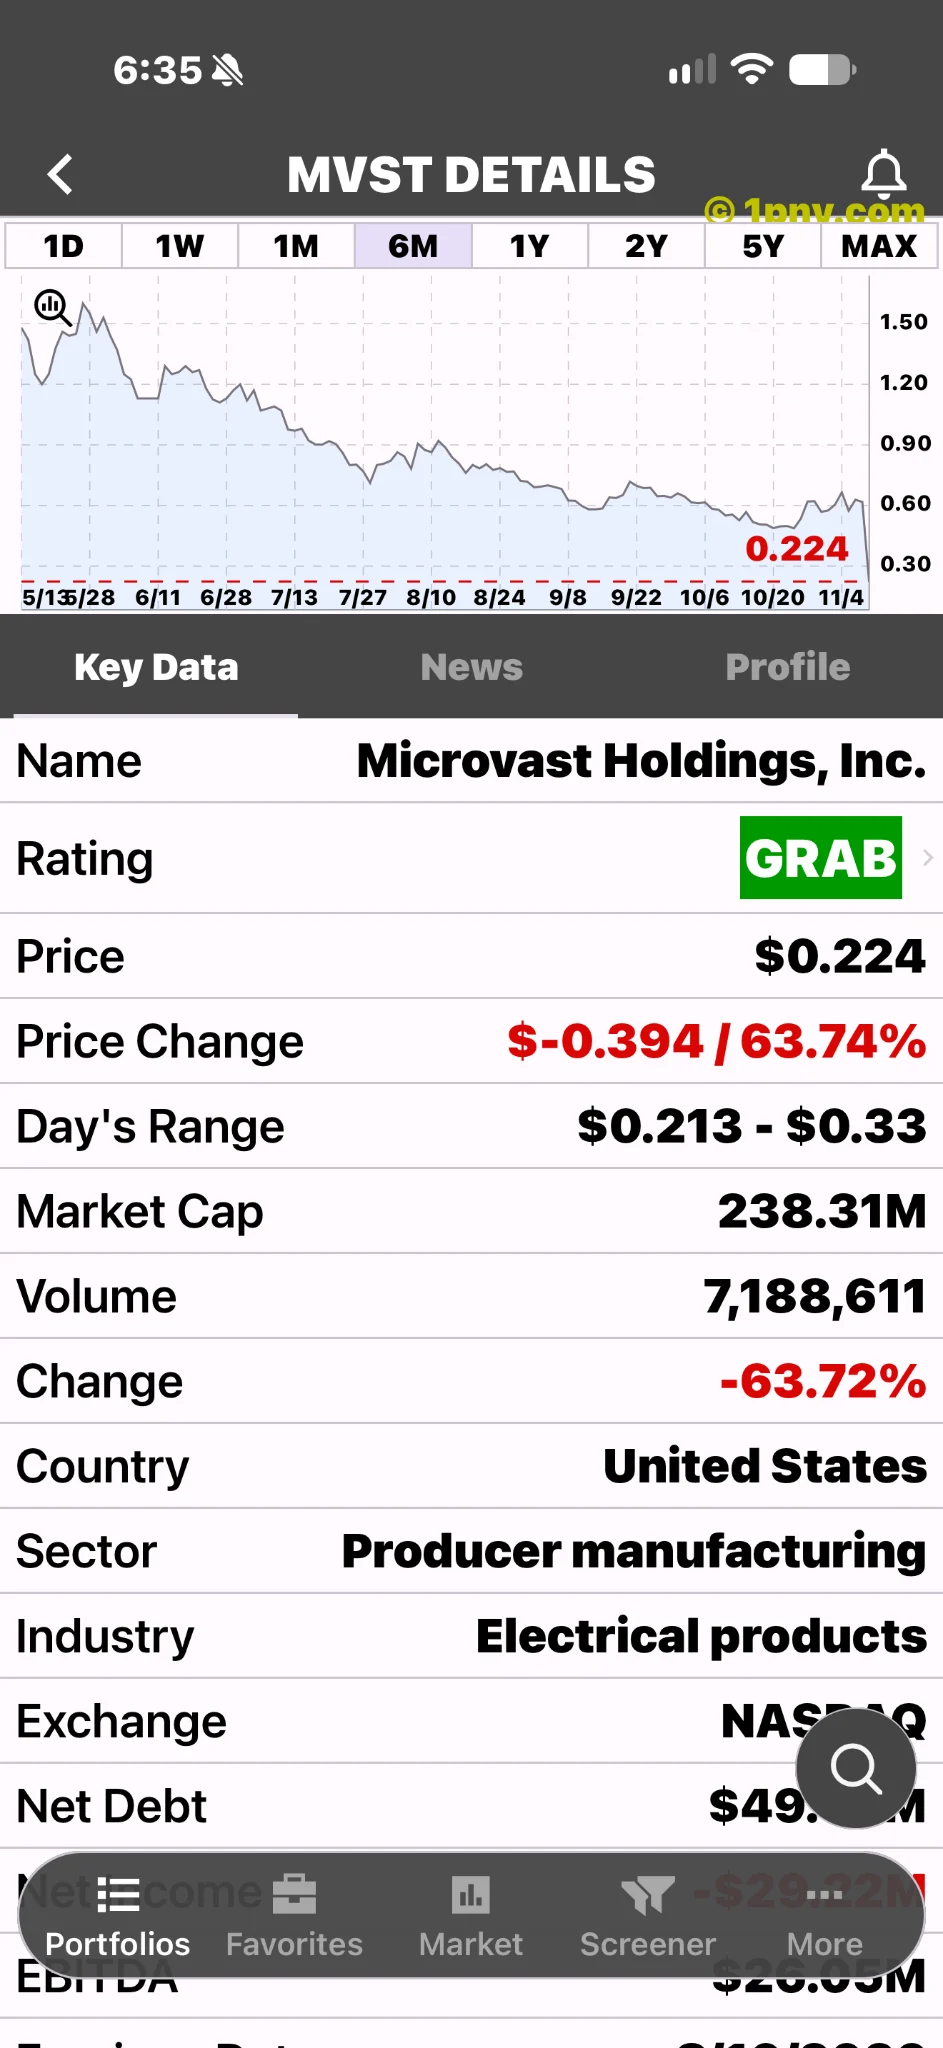
The supplied Penny Gems chart shows MVST near $0.22, down 63.72%, with about 7.17 million shares traded. That is a striking snapshot, not a verified closing result. Our concern is the financial story behind it, rather than the size of the red number alone.
Falling sales make the recovery harder
In its November 9 release, Microvast reported third-quarter revenue of $45.8 million, down 62.8%. Gross margin fell to 5.2% from 37.6%. Management cited weaker commercial-vehicle demand and pricing pressure, while inventory write-downs also hurt margins.
This is the troubling part: the company was not simply waiting for sales growth to return. It retained a much smaller share of the sales it did make after production costs. A recovery in orders would be welcome, but it would need to come with healthier economics to repair the business.
The net loss widened to $76.8 million. Non-cash asset impairments contributed, so it would be wrong to treat the whole loss as an equivalent cash payment. Yet focusing only on those accounting charges would miss the deterioration in sales and margins. In our view, that operating weakness deserves more attention than any argument that the reported loss looks unusually large.
Cash offers breathing room but not a solution
The September 30 filing reported $84.8 million in cash and equivalents, alongside $39.6 million in restricted cash. It is positive that the company reported a cash balance. The restricted portion, however, should not be treated as freely available spending money, and neither figure answers when obligations must be paid.
Management said its projected cash flow would not cover operations and debt payments without further measures. Refinancing, cost cuts and possible asset sales remain uncertain. Its going-concern assessment was not alleviated.
That is the central warning. We would view completed financing on sustainable terms as encouraging; a plan to find financing is a different stage of the story. The distinction matters because creditors and operating needs can absorb resources before any benefit reaches shareholders.
This is a serious funding risk, not an announcement that a bankruptcy filing has occurred. An eventual rescue financing or restructuring could nevertheless leave existing shareholders with substantially less value.
The chart captures fear without proving its source
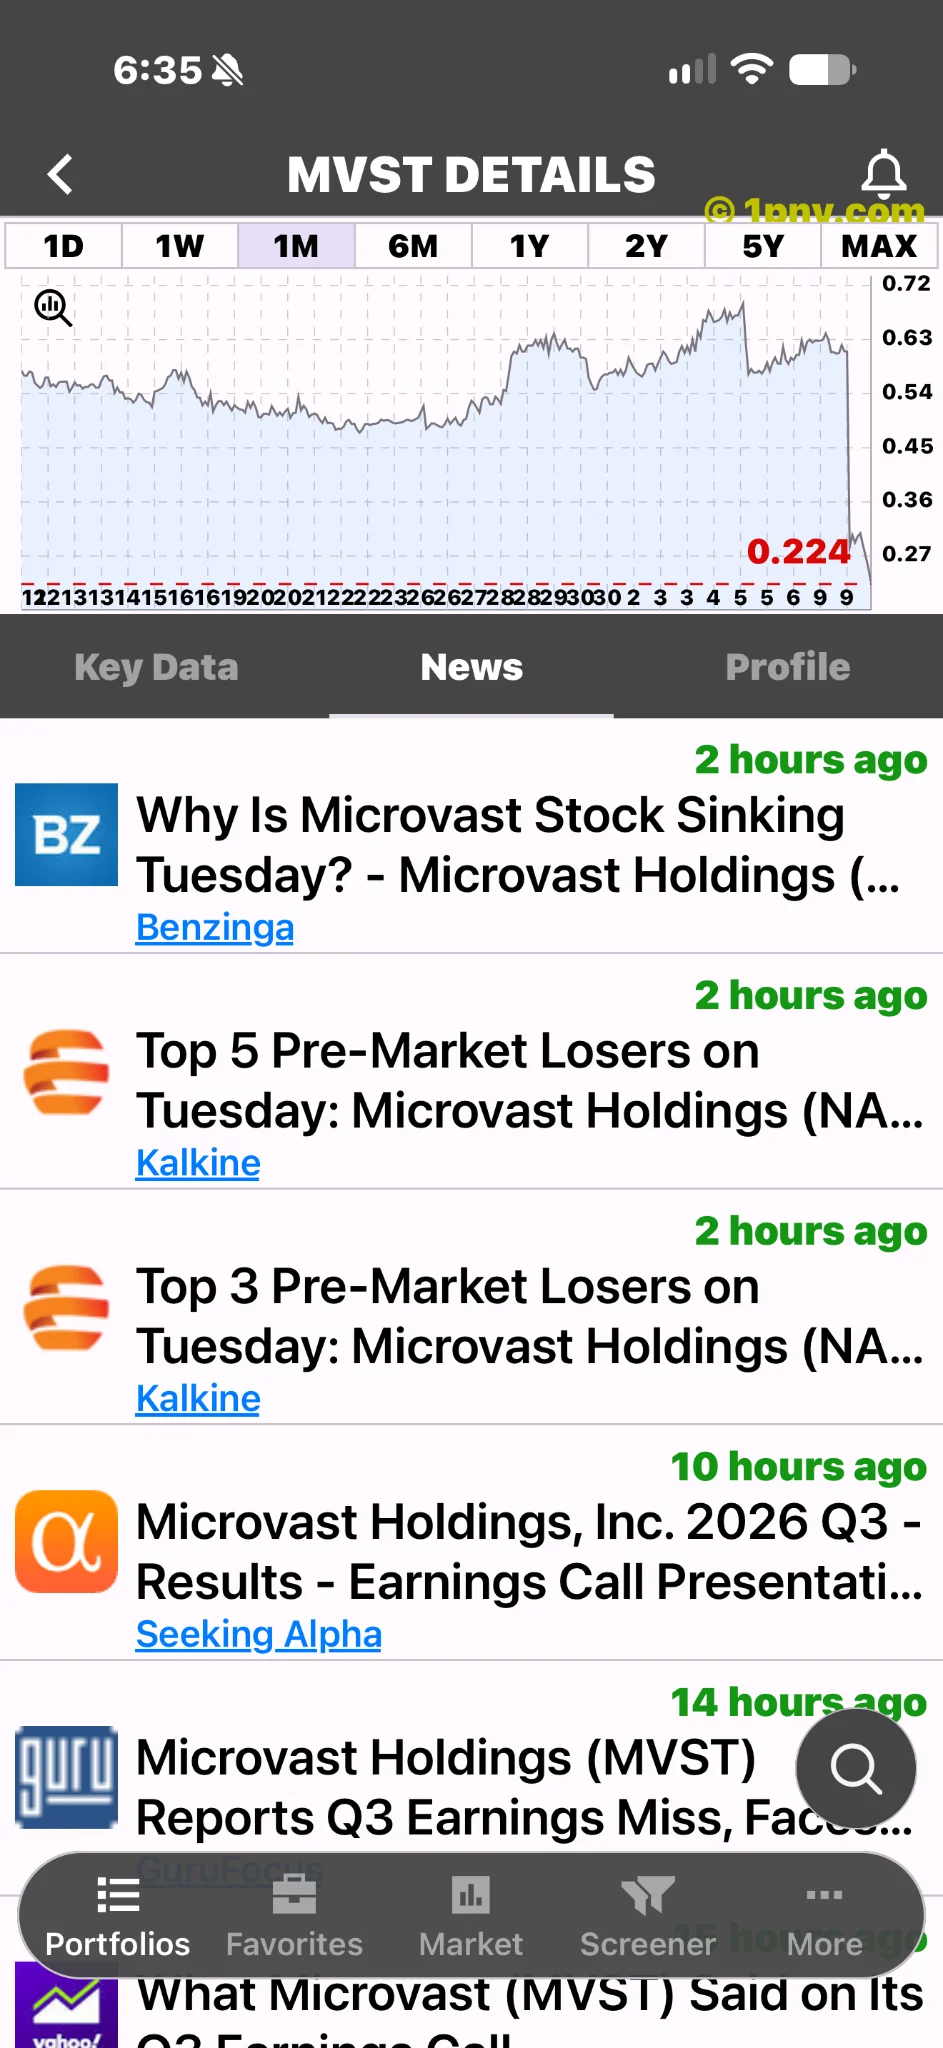
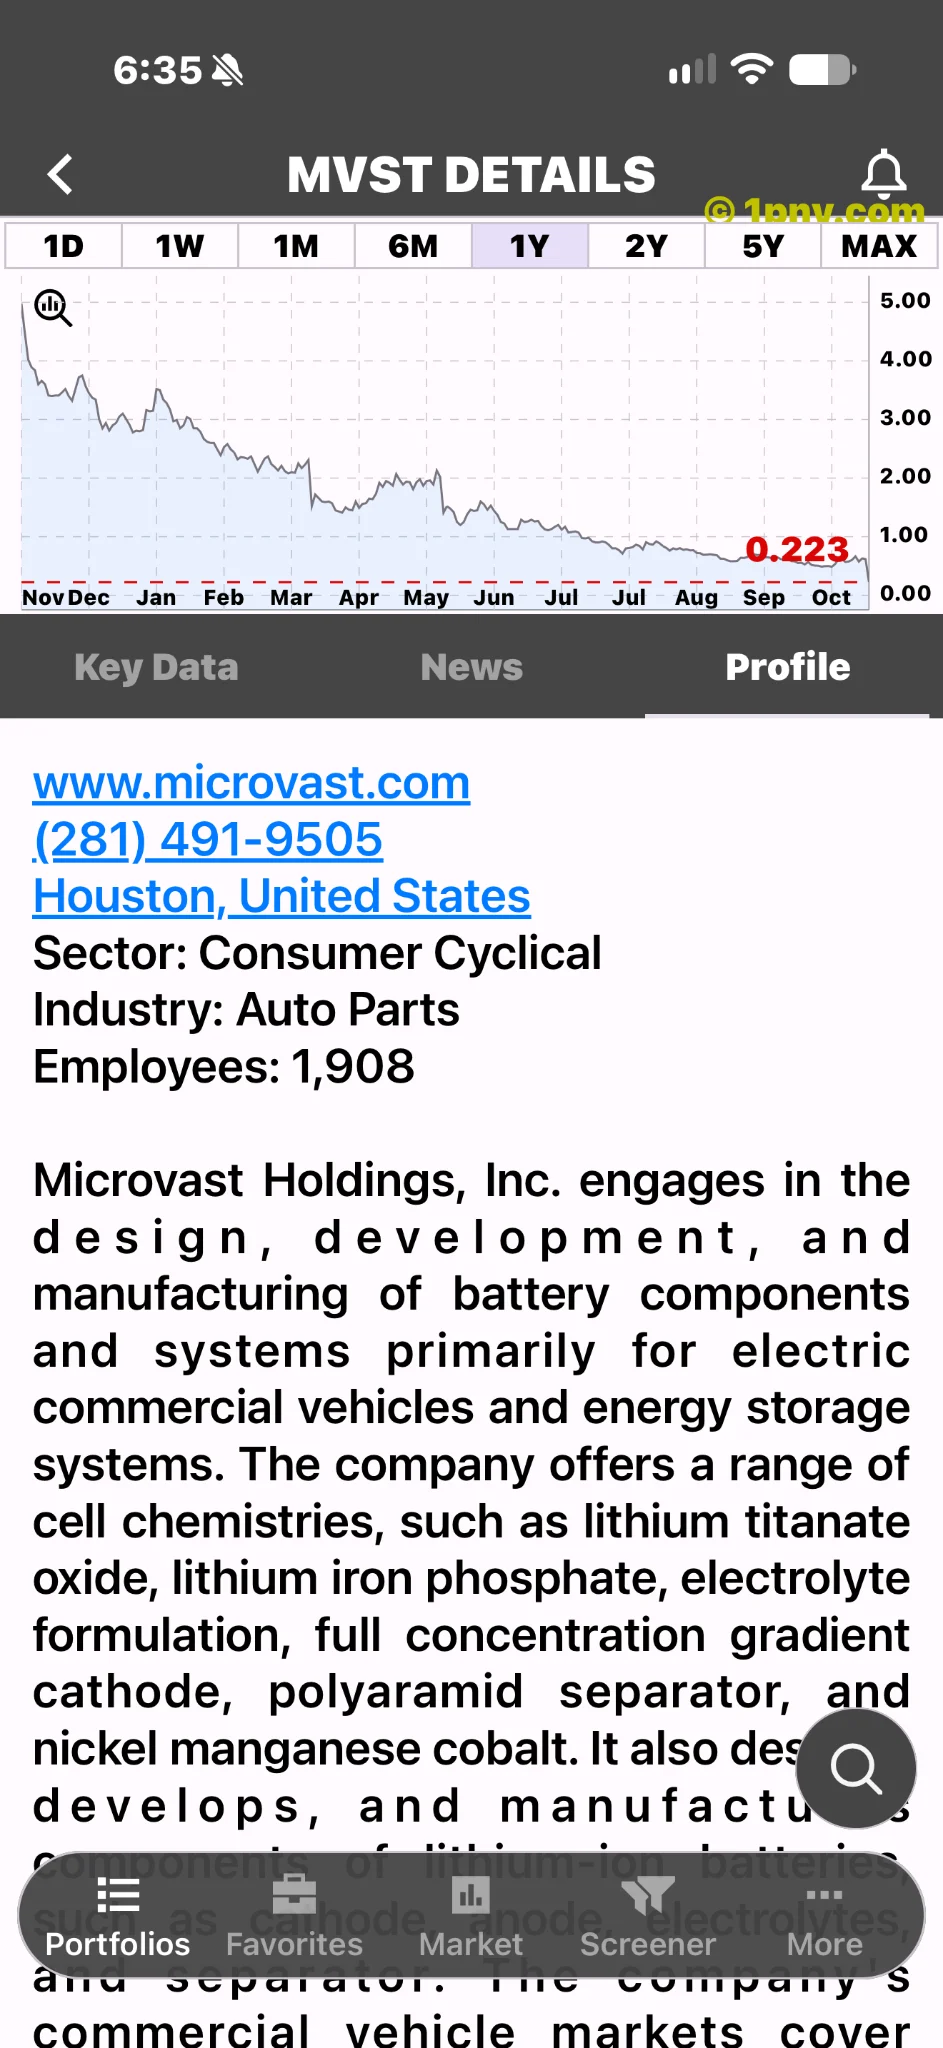
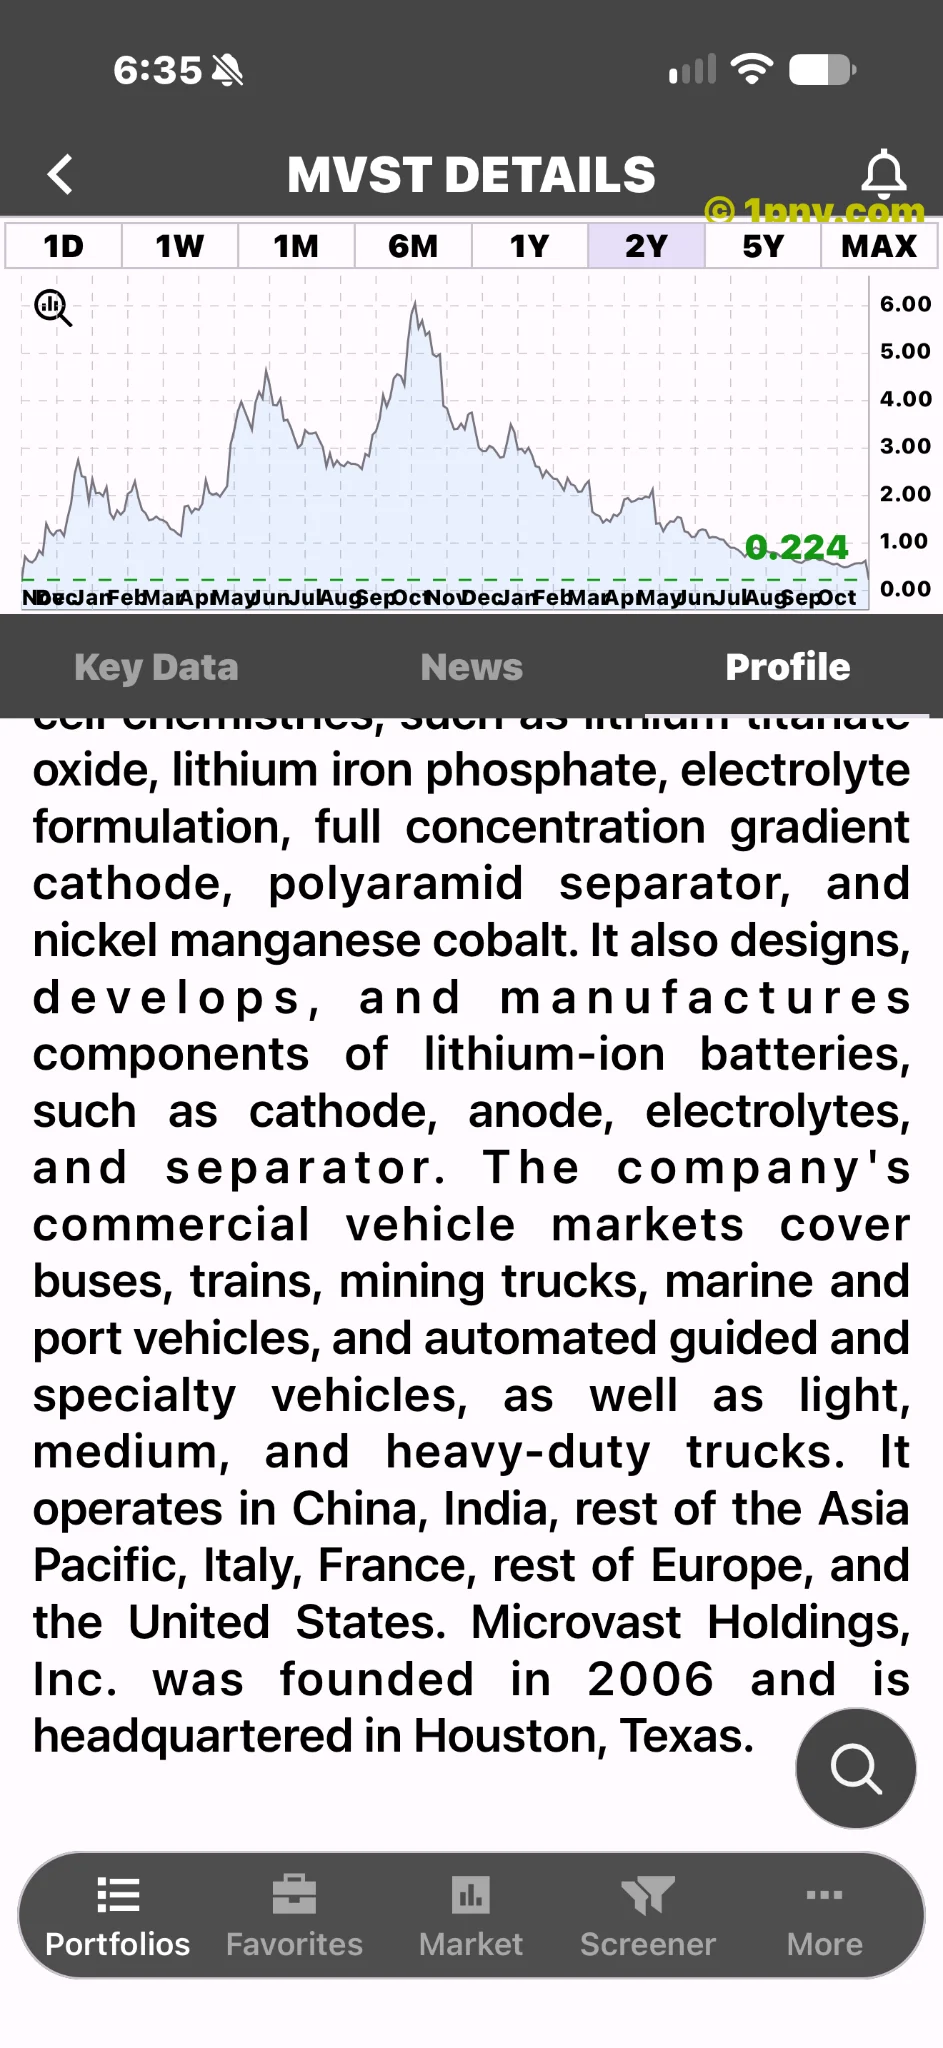
The lead image uses a one-week view. Its displayed percentage should not be relabeled as the week’s return: the chart period and the quote’s comparison period are separate information. Other supplied screens show longer histories, company details and news.
They make the abrupt decline visible, but cannot identify who sold or prove the cause of each trade. The screenshots also lack a complete date with time zone. Their market-cap field has not been reconciled with current shares outstanding, so we do not use it to establish valuation. GRAB is the app’s signal, not this article’s recommendation.
A better ending requires concrete progress
The encouraging development to look for would be signed financing arrangements, stronger cash collections and orders that restore profitable production. Those would change the financial story. A rebound in the share price alone would not.
For now, our assessment is cautious: the company’s earnings and financing disclosures explain why investors have substantial reasons for concern. A low share price does not resolve those problems or tell us where the stock will settle.
For information only. Not investment advice.